Reduce further exposure
If the roof has an opening, call and describe the active concern. Temporary protection is separate from permanent reconstruction. Keep people away from wet electrical equipment and damaged ceilings.
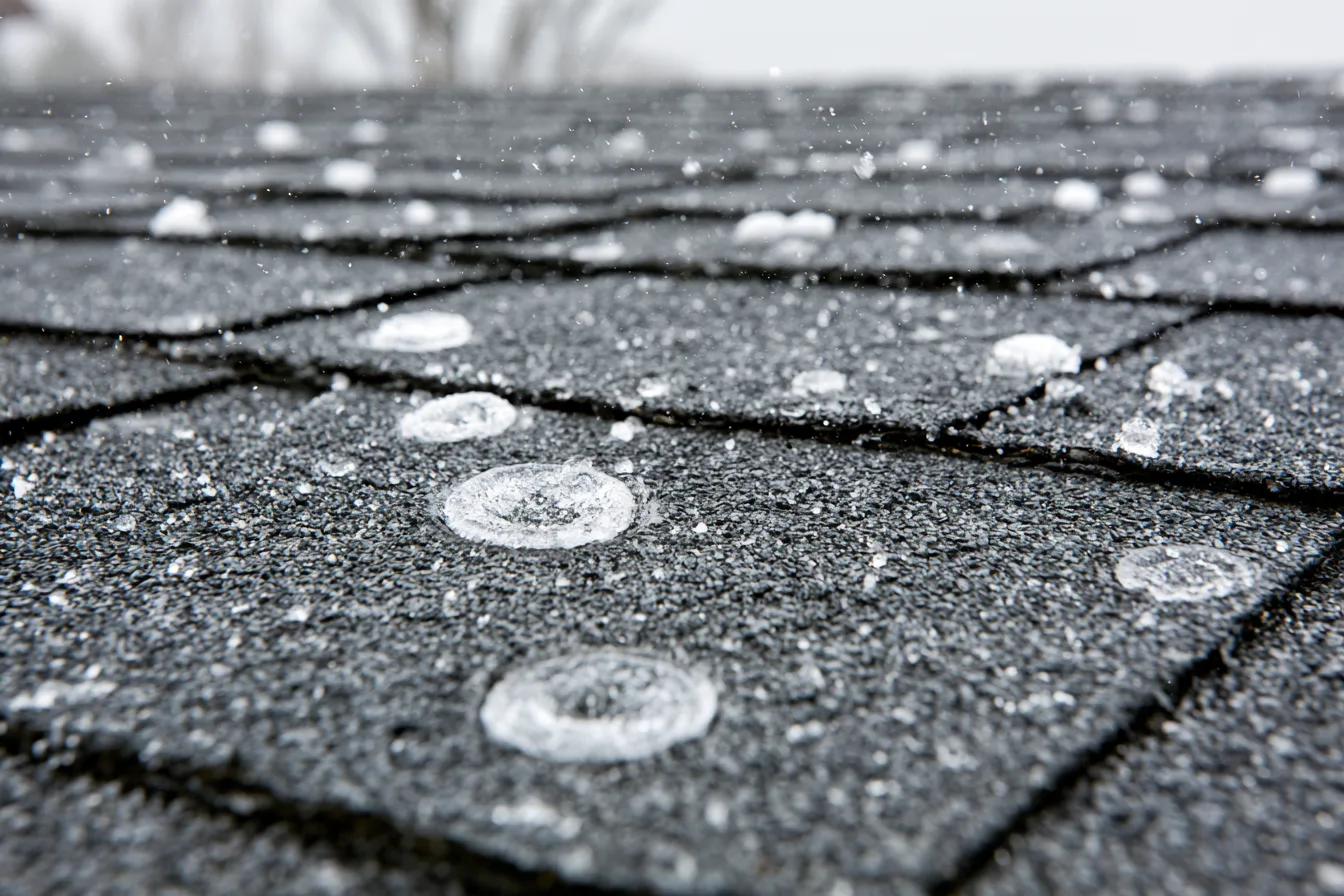
Free roof inspections in Shawnee, Oklahoma
Practical roofing and insurance guidance after wind or hail.
Roof damage and insurance payment are related decisions with different jobs. The inspection evaluates the roof; the insurer decides coverage under the policy.
The Oklahoma Insurance Department post-disaster claims guide explains these terms. Checked October 27, 2026; your own policy and insurer’s decision control the claim.
| Term | What it means for the owner |
|---|---|
| Deductible | The portion of a covered loss the policy places with the insured. A separate wind or hail deductible can apply. |
| Actual cash value | Payment can reflect depreciation under the policy. |
| Replacement cost | The policy’s replacement-cost terms and claim requirements affect how covered work is paid. |
| Exclusions and limits | The cause, condition and policy language determine what is covered. |
A roofing inspection looks at the covering, flashings and visible damage to identify repair needs. Storm reports provide date and location context; they do not prove damage at the property or establish insurance coverage.
The roofing work remains specific to the roof. A repair needs suitable surrounding material and sound connections. Replacement scope includes removal, deck condition and the new system. The claim payment can differ from the project total because of deductibles, depreciation, exclusions or other policy terms.
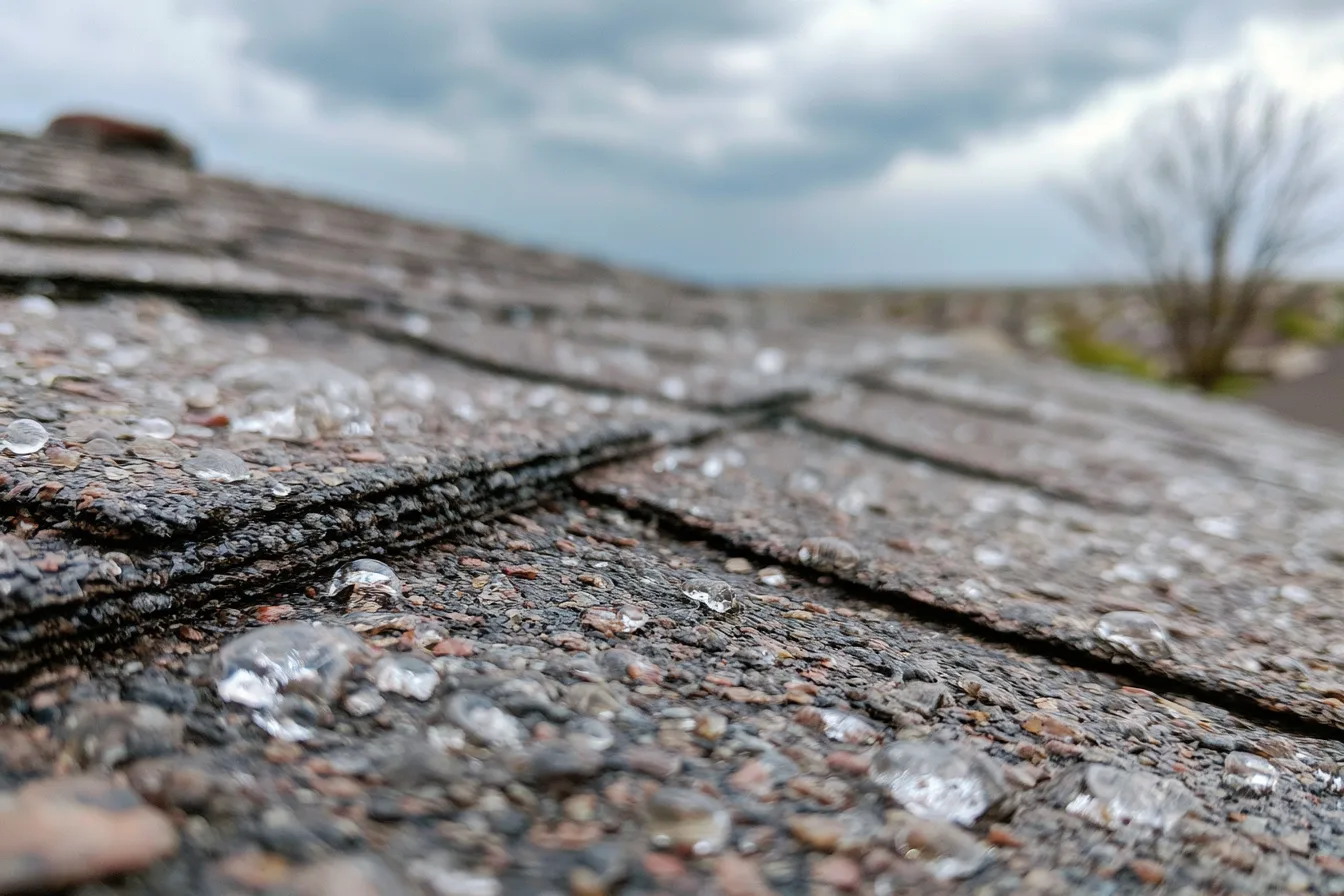
Our storm damage roofing service explains the inspection and the distinction between temporary protection and permanent work.
If the roof has an opening, call and describe the active concern. Temporary protection is separate from permanent reconstruction. Keep people away from wet electrical equipment and damaged ceilings.
The permanent repair or replacement follows the damaged components and the condition of the remaining roof. Insurance administration does not change the need for a sound roofing connection.
No. The roof’s condition and cause of damage need evaluation, and policy terms determine coverage. A nearby hail report alone does not settle either question.
No. The project cost and policy payment are different figures. Deductible, depreciation and other claim terms affect the amount the owner pays.
Request a free roof inspection for the roof concern after the storm.